Capital Gains Tax When Selling a Pierce County Home: Federal Exclusion and Washington Rules
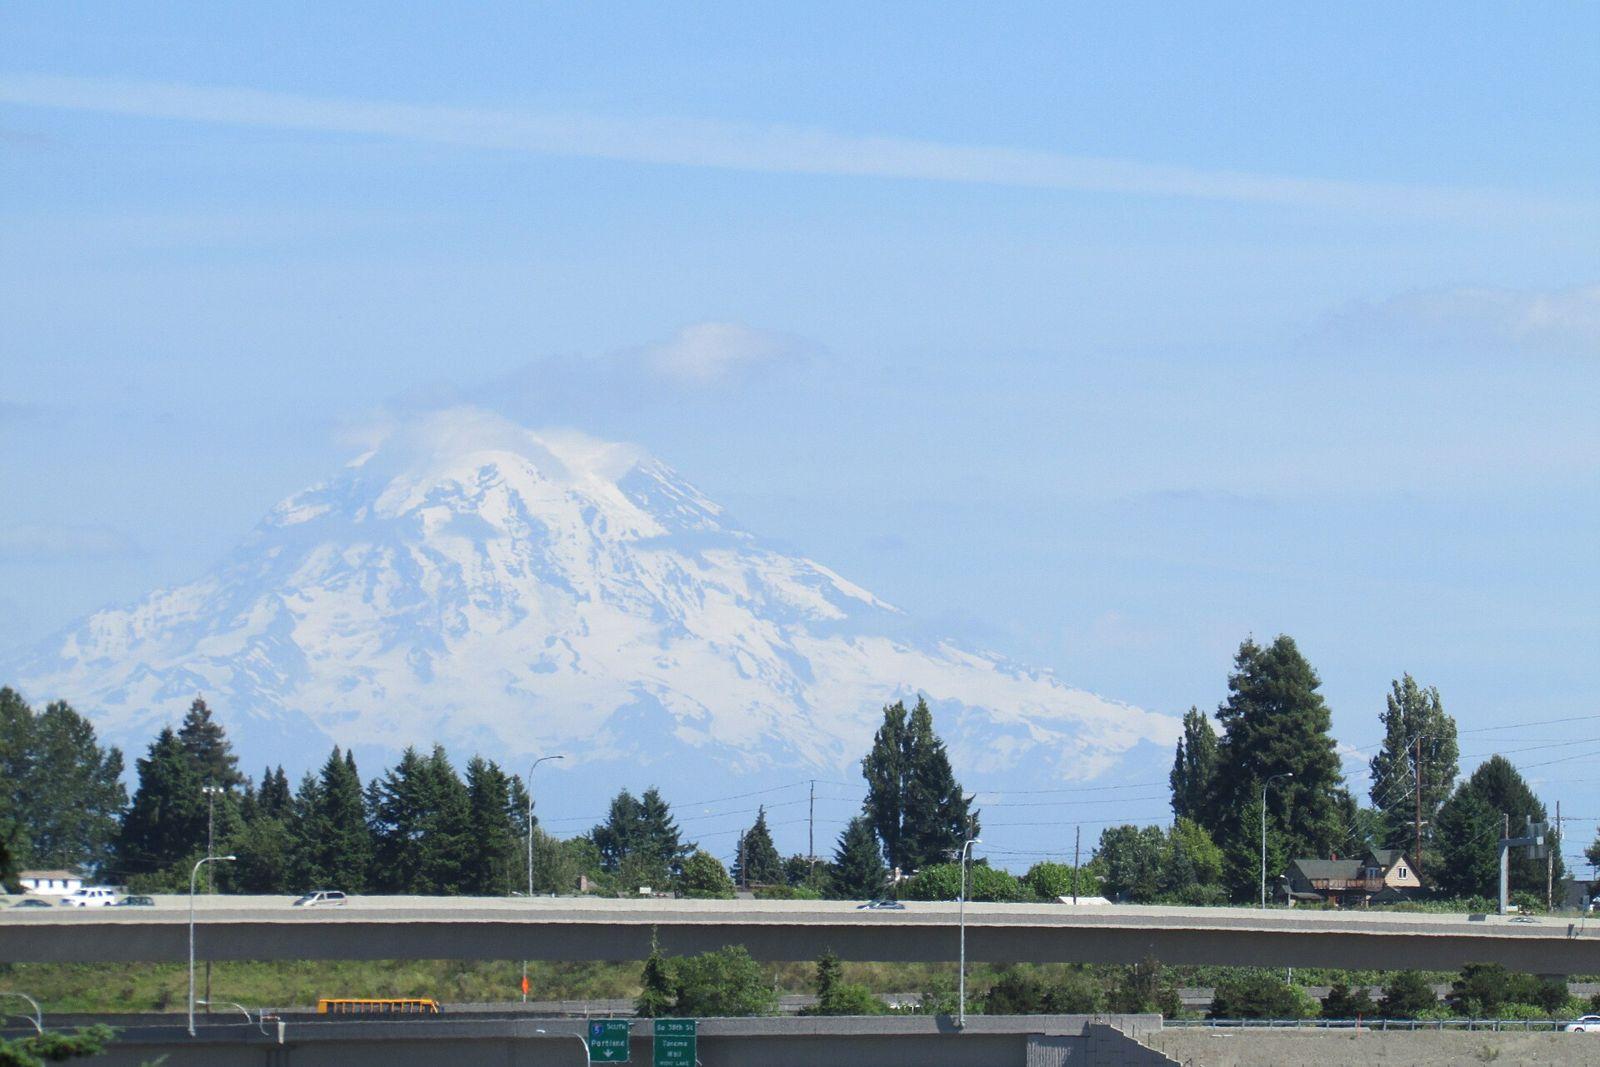
Hero photo: Mount Rainier from Puyallup City Hall by Chris Light via Wikimedia Commons, CC BY-SA 4.0.
Selling a home in Pierce County raises a tax question almost as often as it raises a pricing question: will I owe capital gains tax on the profit?
The short answer is that Washington does not tax the sale of real estate under its capital gains tax. Federal rules are a different story, and they depend on whether the home is your main home, how long you owned and lived in it, and how large the gain is.
This guide is for sellers in Puyallup, Sumner, Tacoma, Bonney Lake, and the rest of Pierce County. It explains the federal exclusion, the Washington rule, and the records to gather before you list. It is general information, not tax advice.
Two different taxes, two different rules
Sellers often mix up federal capital gains tax and Washington REET. They are not the same, and they are calculated differently.
Federal capital gains on a home sale
- Who administers it
- IRS
- What it is based on
- Your gain, after any exclusion you qualify for
Washington capital gains tax
- Who administers it
- Department of Revenue
- What it is based on
- Does not apply to the sale or exchange of real estate
Washington REET
- Who administers it
- State and local rates, paid at closing
- What it is based on
- Usually the selling price, not your profit
The Department of Revenue is clear on the state capital gains question. It does not matter how long you owned the property, whether you lived there, where it is, what type of property it is, or who owns it. The sale of real estate is outside that tax.
Step 1: Know the federal exclusion
IRS Topic 701 and Publication 523 describe the exclusion for the sale of your main home.
- You may qualify to exclude up to $250,000 of gain, or up to $500,000 if you file a joint return with your spouse.
- In general, you must meet both the ownership test and the use test during the five years ending on the date of the sale.
- If you owned the home for at least 24 months out of those five years, you meet the ownership test. For a joint return, either you or your spouse must meet that test.
- If you and, on a joint return, your spouse used the home as a residence for at least 24 months of those five years, you meet the use test. Each spouse must meet the use test individually for the full joint exclusion.
- Generally, you are not eligible if you already excluded gain from another home sale during the two years before this sale.
Publication 523 also explains that you have only one main home at a time, and it walks through how to decide which home that is if you own more than one.
Illustrative sale price
- Amount
- $650,000
Illustrative adjusted basis
- Amount
- $300,000
Illustrative gain
- Amount
- $350,000
Exclusion if a qualifying joint return applies
- Amount
- $350,000 of the $500,000 maximum, in this illustration
These numbers are only an illustration of how an exclusion can cover a gain. They are not a market figure, and they are not your tax result. Your basis, selling costs, and filing status change the math.
Step 2: Figure your gain the right way
The exclusion applies to your gain, not to the sale price. In broad terms, gain is what you receive for the home minus your adjusted basis.
Adjusted basis usually starts with what you paid, then changes with qualifying improvements and certain other adjustments. Publication 523 has the worksheets. Keep records for:
Step 3: Watch for situations that change the result
The full exclusion is for a qualifying sale of your main home. Other facts can change what you owe or how you report the sale.
- 1You have not met the 24 month tests. Publication 523 describes limited exceptions and possible partial exclusions. Do not assume you qualify.
- 2You used the home as a rental or a second home. The exclusion may be reduced or unavailable, and depreciation can have its own tax effect.
- 3You inherited the home. Basis rules are different. See our guide to selling an inherited home in Pierce County, and confirm basis with a tax professional.
- 4You already used the exclusion on another sale in the prior two years.
Step 4: Know when you still have to report the sale
Even if you can exclude all of the gain, you may still have to report the sale. Topic 701 says that if you receive an informational document such as Form 1099-S, you must report the sale even if the gain is excludable. You also must report it if you cannot exclude all of the gain.
The IRS points to Schedule D and Form 8949 when a sale has to be reported. Your tax professional can tell you what applies to your return.
Step 5: Put taxes next to your net sheet
Tax is only one piece of what you take home. REET, title, escrow, and brokerage compensation still come out at closing, whether or not you owe federal tax on the gain.
- Work through seller closing costs so the closing statement and the tax picture are not mixed together.
- Get a current value picture with a free home evaluation or read what's included in a home evaluation.
- If you are selling and buying at the same time, see should you sell your home before you buy a new one.
FAQ
Do I owe Washington capital gains tax if I sell a rental or vacant land?
The Department of Revenue says the state's capital gains tax does not apply to the sale or exchange of real estate, including different property types. Federal tax can still apply. Ask a tax professional about your property.
Can I use the $500,000 exclusion if I am married?
Only if you file a joint return and you both meet the use test, with at least one spouse meeting the ownership test, as Topic 701 describes. Confirm your filing status and dates with a tax professional.
Does a higher sale price automatically mean I will owe tax?
No. The exclusion is based on gain, not price. A higher price can still produce a gain inside the exclusion if your basis is high enough, or a taxable amount if it is not.
Should I delay a sale to meet the two year tests?
That depends on your dates, your housing needs, and the rest of your tax picture. Publication 523 is the starting point, and a tax professional should review the timing with you.
This article is general information, not tax or legal advice. Federal and state rules depend on your facts and can change, so confirm your situation with a qualified tax professional before you list or file.
Ready to Take Action?
Let's Talk About
Your Home.
Whether you're ready to sell, curious about your home's value, or just have questions — our team is here to help with honest, local expertise in Lake Tapps, Puyallup, Bonney Lake, and across Pierce County.