First-Time Home Buyer Guide for Pierce County: Costs, Steps, and Washington Help
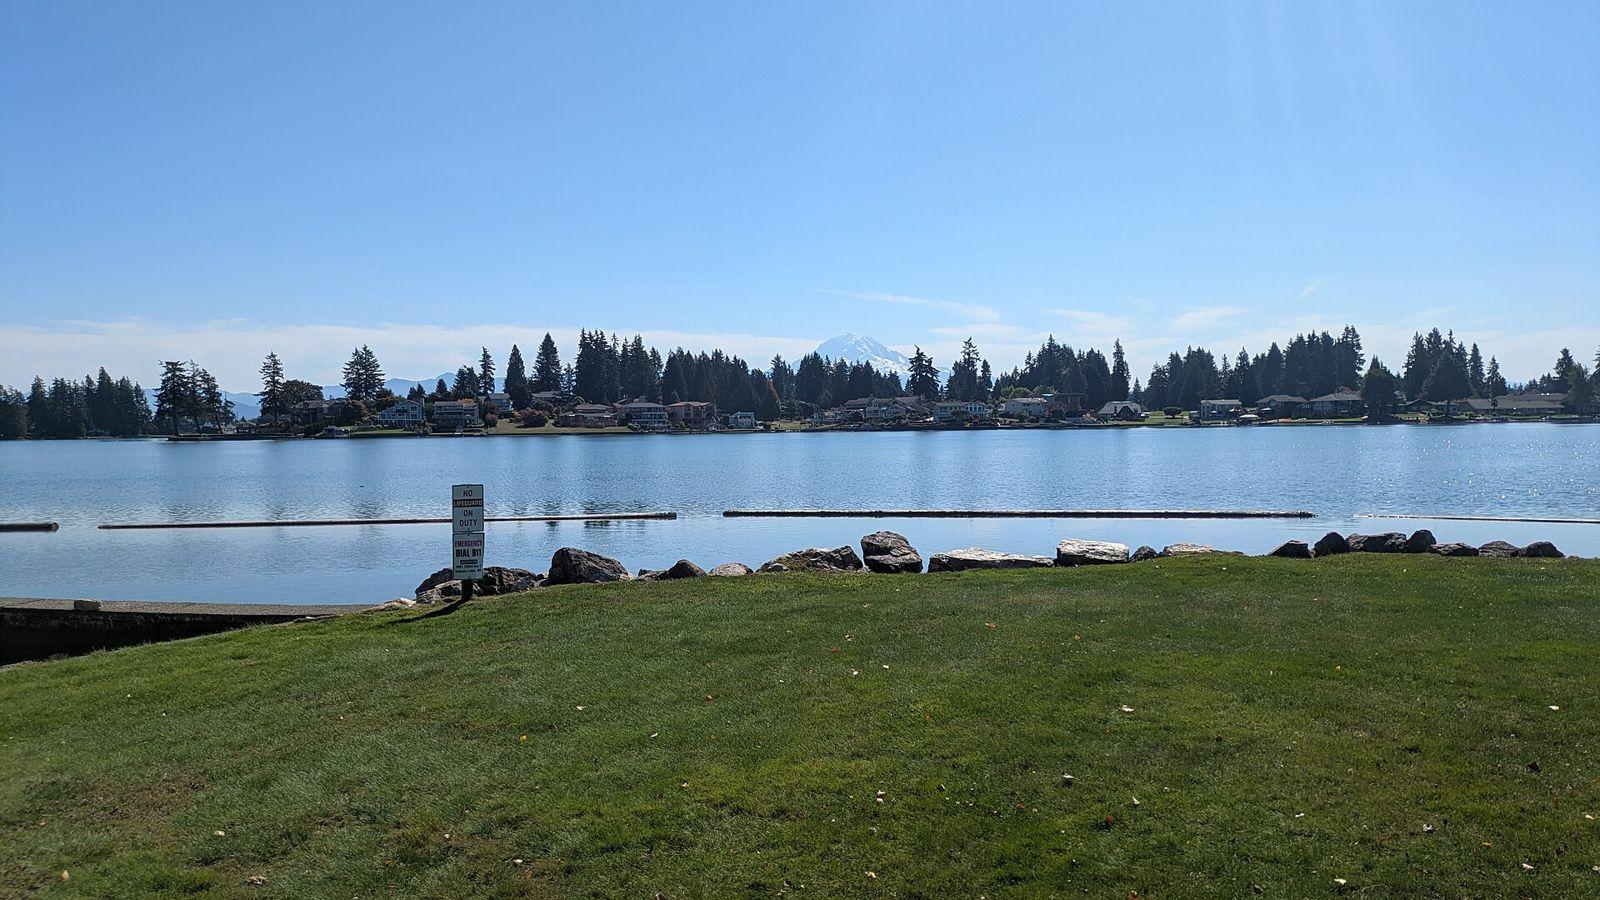
Hero photo: Lake Tapps by Laketappsenjoyer via Wikimedia Commons, CC0.
Searching "what should a first time home buyer know" brings up a lot of national advice that skips the local details. In Pierce County, those details matter. Septic systems, lake rules, newer master planned neighborhoods, and Washington's own paperwork all change how a purchase plays out.
This guide walks through the full path in the order you will actually live it. It covers the costs people forget, the free Washington programs worth a phone call, and the official rules that protect you at the lender and with your agent.
Short on time? Skip ahead to the Pierce County checks or the cost table.
Step 1: Get your money picture clear
Before you open a single listing, look at your credit reports and your spending. The CFPB's prepare to shop guide suggests checking your reports for errors early so you have time to fix them, and tracking your spending to understand what monthly payment you can really carry.
Then decide on a payment, not just a price. Taxes, insurance, utilities, and upkeep all sit on top of the mortgage, so the number your lender approves is a ceiling, not a target. Our post on the real cost of buying in Pierce County shows why taxes and insurance deserve their own line.
Step 2: Learn what Washington help exists
Many first-time buyers assume down payment help is out of reach. Washington runs real programs, and a few phone calls can change your numbers.
Home Advantage down payment assistance
- What it offers
- 3%, 4%, or 5% of the first mortgage loan amount, at 0% interest, with no monthly payments. Due when you sell, refinance, transfer, stop living in the home, or pay off the loan
- Where to start
- Here to Home (WSHFC)
Needs based option
- What it offers
- Up to $10,000 at 1% simple interest, with a needs assessment required for most borrowers
- Where to start
- Here to Home (WSHFC)
Homebuyer education class
- What it offers
- Free class sponsored by the Commission, required for Home Advantage. Your certificate is valid for two years
- Where to start
- Home Advantage page
Free state counseling
- What it offers
- Counseling for Washington residents thinking of buying a home
- Where to start
- DFI homeownership page
One useful detail from the program page: the Commission says your lender can lock your rate after you have a fully executed purchase and sale agreement and after you have taken the class. Take the class early so it never slows your timeline.
Step 3: Pick your lender and read the Loan Estimate
Talk with more than one lender, then compare offers on paper. The CFPB says each lender must send you a Loan Estimate within three business days after you submit the key application details. It also notes a Loan Estimate is not an approval, and you are not committed to any lender until you sign final closing documents.
Loan Estimate
- When you get it
- Within three business days of your application
- What to do with it
- Compare offers side by side, and ask about anything that differs from what you discussed
Closing Disclosure
- When you get it
- At least three business days before closing
- What to do with it
- Compare it with your latest Loan Estimate, including the APR and cash to close
Step 4: Work with an agent and understand your agreement
In Washington, a buyer's agent works under a written services agreement with their firm. RCW 18.86.120 says it must be entered into before, or as soon as reasonably practical after, the broker begins rendering services.
The state's summary lists what the agreement must contain, and a few of those items deserve a slow read.
Term of the agreement
- Why it matters to you
- Know when it starts and ends. RCW 18.86.020 sets a default of 60 days for buyers, with the option of a longer term
Exclusive or nonexclusive
- Why it matters to you
- Exclusive means you cannot work with another firm during the term
Limited dual agency consent
- Why it matters to you
- Decide whether you consent, and read what it means
Terms of compensation
- Why it matters to you
- Know how your agent is paid, and in what situations you might owe something
Showing when no compensation is offered
- Why it matters to you
- Ask whether your agent will show you a home in that case
Our deeper guide on how to compare buyer's agents in Lake Tapps, Bonney Lake, and Auburn gives you interview questions to bring to that meeting. If you want a general refresher on our buying services, visit our buy a home page.
Step 5: Do the Pierce County checks
National checklists rarely mention the questions that matter on the plateau and in the valley. Put these on your list before you write an offer.
- Septic or sewer: confirm which one the home uses, and read our guide to Pierce County septic systems for buyers and sellers.
- Inspection: plan for a full inspection, and read our Bonney Lake and Lake Tapps inspection guide so you know what the report should cover.
- Community rules: if there is an association, read the dues, rules, and documents before your contingency period ends.
- Lake rights: for homes near Lake Tapps, ask for written details about any dock or shoreline access that comes with the property.
- Your commute: drive your real route at your real time before you commit.
Step 6: Plan for the costs people forget
Your down payment is only one part of the cash you will need. Use this table to make sure every category has a line in your plan, then ask your lender for the real numbers.
Down payment
- When it shows up
- At closing
- Where to get the number
- Your loan program and lender
Earnest money
- When it shows up
- When your offer is accepted
- Where to get the number
- Your offer and your agent
Home inspection
- When it shows up
- During your inspection period
- Where to get the number
- The inspector's quote
Appraisal
- When it shows up
- During your loan process
- Where to get the number
- Your Loan Estimate
Closing costs
- When it shows up
- At closing
- Where to get the number
- Your Loan Estimate and Closing Disclosure
Taxes and insurance set aside
- When it shows up
- At closing and monthly
- Where to get the number
- Your lender and your insurance quote
Moving, utilities, and first repairs
- When it shows up
- After you get the keys
- Where to get the number
- Your own budget
If a low appraisal ever slows things down, our seller side post on how to handle a low appraisal explains how the negotiation tends to work from the other side of the table.
Step 7: Close safely
By law you receive your Closing Disclosure at least three business days before closing, and the CFPB advises you to use that time. Compare it line by line with your Loan Estimate, and do not sign until you understand each number.
- 1Contact your lender or closing agent at least a week before closing to confirm how you will receive your Closing Disclosure.
- 2Compare it with your latest Loan Estimate, including the loan amount, rate, monthly payment, and cash to close.
- 3Ask questions about any change, and have your agent review the other documents with you.
- 4Confirm your funds and the final walkthrough details.
- 5Sign only after every number makes sense to you.
Where to look first
Every first-time buyer ends up comparing places. Our area guides cover Puyallup, Sumner, Bonney Lake, and Lake Tapps, and you can browse current listings or open houses to see what your budget buys. If you already own a home and want to buy another, read about selling before you buy.
For a shorter checklist version of this guide, see our earlier post on six essential things every first-time homebuyer should know.
Common questions
How much do I need to buy my first home in Washington?
It depends on your loan program, price, and closing costs. Down payment help from the Washington State Housing Finance Commission can cover part of it, and your lender can show your exact cash to close on the Loan Estimate.
Do I have to be a first-time buyer to use Washington down payment help?
Not for Home Advantage. The Commission says first-time homeownership is not required, but the home must be your principal residence, and income limits apply.
Can my lender change my costs after the Loan Estimate?
Some fees cannot rise, some are limited to a 10 percent increase, and some can change without a limit, per the CFPB. Compare your Closing Disclosure against your Loan Estimate and ask about every difference.
This article is general information, not legal, tax, or financial advice. Program rules and income limits change, so confirm current requirements with the sources linked above and with a licensed lender or qualified professional before acting.
Ready to Take Action?
Let's Talk About
Your Home.
Whether you're ready to sell, curious about your home's value, or just have questions — our team is here to help with honest, local expertise in Lake Tapps, Puyallup, Bonney Lake, and across Pierce County.